
🔍 Read the full analysis: The AI Data Center Boom’s Price Tag: From Investors To Power Bills on ThorstenMeyerAI.com

Get hardware and tech essentials delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
TL;DR
Amazon, Microsoft, Alphabet and Meta spent about $202 billion on property and equipment in the third quarter of 2026, more than twice the amount a year earlier, according to the source’s calculation from company filings. The companies are combining cash, debt, leases, partnerships and share sales to fund AI infrastructure. The long-term costs and how they will be distributed remain uncertain.
Amazon, Microsoft, Alphabet and Meta spent about $202 billion on property and equipment from July through September 2026, more than twice their combined spending a year earlier, according to a calculation based on company cash-flow statements. The companies are also using debt, leases, partnerships and share sales to finance data centers, servers and chips as investment in AI infrastructure increases.
The source’s calculation puts the four companies’ combined property and equipment spending at about $202 billion in the third quarter, compared with about $97 billion in the same period of 2025. Amazon reported $77.3 billion, Alphabet $51.4 billion, Microsoft $39.4 billion in cash capital spending and Meta $33.9 billion. Microsoft’s figure rises to $45.2 billion when new finance leases are included, according to its filing.
Company forecasts point to spending continuing at a high level. Amazon said it expected about $220 billion in cash capital spending for 2026, and said the increase primarily reflected AI investments. Alphabet kept its 2026 capital-spending outlook at $195 billion to $205 billion and expected a significant increase in 2027. Microsoft expected about $170 billion for calendar 2026, while Meta forecast $135 billion to $145 billion, including finance-lease payments.
The financing mix is changing alongside the spending. The source reports that Meta sold $25 billion in its own stock and $12.5 billion in preferred shares, Microsoft issued $25 billion in bonds, and Amazon disclosed a loan of up to $80 billion secured by servers it plans to purchase. The source also calculates that Amazon, Alphabet and Meta raised about $225 billion in long-term debt in the first nine months of 2026. These deals are company-specific; the figures do not mean that every dollar raised is exclusively for AI infrastructure.
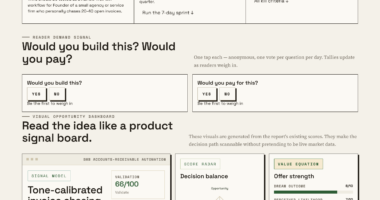
Infographic 01 · One quarter, four companies
The bill doubled. The cash did not.
What Amazon, Microsoft, Alphabet and Meta paid for buildings, servers and chips from July to September 2026, set against the cash their businesses brought in.
AmazonQ3 2025: $35.1B spent
Spent $34.9B more than came in
AlphabetQ3 2025: $24.0B spent
Free cash flow −$9.1B
MicrosoftQ3 2025: $19.4B spent
$18.6B left over
MetaQ3 2025: $18.8B spent
Free cash flow −$2.1B
Cash purchases of property and equipment as reported; not all of it is for AI (Amazon also builds warehouses). Gaps for Amazon and Microsoft are my arithmetic; free cash flow for Alphabet and Meta as the companies report it. Microsoft’s quarter is its fiscal Q1 2027 (July–September 2026).
Sources: Amazon results, 29 Oct · Microsoft 10-Q, 28 Oct · Alphabet results, 28 Oct · Meta results, 21 Oct. Debt raised: cash flow statements, nine months 2026.
Powered by Thorsten Meyer AI
How AI Infrastructure Gets Funded
The spending figures and financing disclosures describe how the companies are funding infrastructure for AI services. Data centers require computing equipment, buildings, land, electricity and long-term agreements. When cash spending exceeds funds generated by operations, companies may use financing involving bondholders, lenders, property investors and shareholders, alongside their own balance sheets.
The source calculates that three of the four companies spent more on property and equipment in the quarter than their businesses generated in operating cash. That comparison is not a complete measure of financial health: companies have other sources of cash, and quarterly spending can fluctuate. The source reports trailing-12-month free cash flow of negative $42.4 billion for Amazon, and quarterly free cash flow of negative $9.1 billion for Alphabet and negative $2.1 billion for Meta. Microsoft was the only one of the four described as clearly positive on the comparison.
Data centers require substantial electricity, and the source identifies long power contracts as one cost connected to the build-out. Whether those agreements affect local power bills depends on how power supply, infrastructure investment and utility costs are allocated. The supplied material does not establish that households are already paying more because of these companies’ projects.
Products Worth Considering

LG UltraGear 27-Inch QHD OLED Gaming Monitor, 240Hz, 0.03ms, G-SYNC Compatible, FreeSync Premium Pro, HDMI 2.1

Apple MacBook Pro 14 (2021) with M1 Max, 64 GB RAM, 2 TB SSD, Silver

Logitech MX Brio Ultra HD 4K Webcam, Graphite
As an affiliate, we earn on qualifying purchases.
The Commitments Beyond Quarterly Spending
Capital spending is only one part of the longer-term financial picture. According to the source’s sum of four company filings, the companies had about $1.02 trillion in future lease payments as of September 30, 2026, primarily connected to leases that had not yet started. The source says this total is more than twice their combined long-term debt. These are future commitments, not bills paid in the third quarter, and the figure reflects the source’s calculation across the four filings.
The financing tools differ in who supplies money and who holds particular obligations. Operating cash avoids interest payments. Bonds and loans provide funds that must be repaid, while leases allow a company to use facilities or equipment in exchange for contracted payments. A separate property owner or project company can finance a building and lease it to a technology firm; equity financing brings in investors in exchange for ownership stakes. The source describes the companies as using a mix of these approaches, alongside power agreements.
The time horizons do not always match. The source says servers are written off over roughly five to six years, while power contracts may last 15 to 20 years, data-center leases up to 20 years and some bonds as long as 40 years. If AI-related income grows more slowly than infrastructure costs, companies and their financing partners could face a gap between expected returns and contractual payments. That is a risk scenario, not a confirmed forecast.
Who Bears the Long-Term Costs
The available figures show spending, financing announcements and disclosed commitments, but they do not establish how profitable the new infrastructure will be. It remains unclear how quickly AI services will generate revenue relative to the cost of building and operating data centers, or how fully current facilities will be used. The source’s discussion of newer GPU cloud providers and companies that own data-center buildings describes possible risks, not confirmed losses for those firms.
The supplied material does not establish how much of the financing is specifically tied to AI projects, what conditions apply to every reported loan or lease, or whether power costs will be passed on to electricity customers. The $1.02 trillion lease estimate combines future payments and should not be read as an amount immediately due. The source’s spending totals are its own sums of company filings; they are not a single combined figure reported by the companies themselves.
Company Spending and Financing Updates
Future company filings and earnings updates will report actual capital spending, operating cash generation, debt and lease commitments, and changes to annual forecasts. Those figures can be compared with the companies’ stated expectations for 2026 and, in Alphabet’s case, its outlook for higher spending in 2027. The supplied material does not identify a specific upcoming financing deadline or regulatory decision.
For power customers and local communities, relevant developments include whether new data-center projects require additional electricity infrastructure and how costs are assigned among utilities, operators and customers. The effects will vary by location and cannot be inferred from national company spending totals alone. Further disclosures may clarify the expected returns and how costs are allocated among companies and other parties.
Key Questions
How much did the four companies spend in the third quarter of 2026?
The source calculates that Amazon, Alphabet, Microsoft and Meta spent about $202 billion on property and equipment from July through September 2026, compared with about $97 billion a year earlier. The total is the source’s sum of company cash-flow statements.
Why are major technology companies borrowing and using other financing?
Their spending on data centers, servers and chips has grown to a level that exceeds operating cash in some quarterly comparisons. Companies are using a mix of cash, bonds, loans, leases, partnerships and equity; the specific mix differs by company.
Does the $1.02 trillion lease figure mean the companies owe that amount now?
No. It is the source’s estimate of future lease payments, mostly for data centers, that had not started as of September 30, 2026. It is a long-term commitment estimate, not an amount immediately payable.
Will the AI data-center build-out raise household electricity bills?
The supplied material does not confirm that household bills have risen because of these projects. Data centers require electricity and long-term power arrangements, but any effect on customers depends on local power supply, infrastructure costs and how those costs are allocated.
What is the main financial risk described in the report?
The source highlights a possible mismatch between the useful life of equipment and the longer duration of leases, power contracts and some bonds. If AI revenue grows more slowly than the related costs, companies or their financing partners may have to carry the difference; that outcome is a risk scenario, not a confirmed result.
Source: ThorstenMeyerAI.com